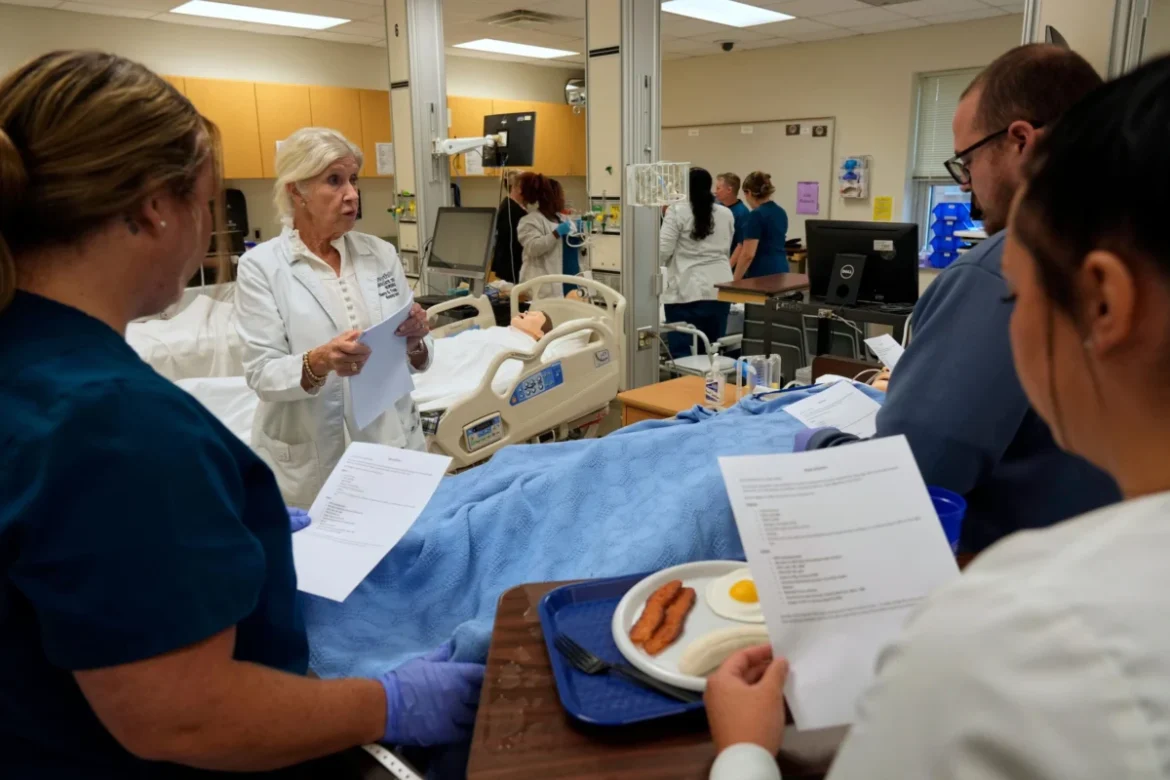
The landscape of American graduate education is currently defined by a profound sense of instability as a legislative overhaul of federal student lending collides with ongoing litigation, leaving thousands of prospective students in a state of financial limbo. For Mitzie Westgate, a 21-year-old senior at the College of Charleston, the pursuit of a doctorate in occupational therapy—a career path inspired by her cousin’s experience with cerebral palsy—has transformed from a clear professional trajectory into a logistical puzzle. With federal loan limits suddenly tightened and the future of those caps subject to a pending court decision, Westgate and peers across the nation are unable to finalize their graduate school applications, unsure if they will be able to afford the programs that offer the best training and networking opportunities.
The confusion stems from a legislative maneuver enacted last year, which removed numerous graduate-level programs from the Department of Education’s list of recognized professional degrees. This reclassification imposed strict annual and lifetime borrowing caps on federal loans, effectively ending the former Grad PLUS program that previously allowed students to borrow up to the total cost of attendance. Under the new guidelines, which took effect on July 1, most graduate students are limited to $20,500 annually and a $100,000 lifetime limit. While 11 specific professional programs were granted higher tiers of $50,000 annually and $200,000 total, the majority of health care and psychology fields were excluded, creating a financial cliff for students pursuing essential but high-tuition degrees.
A Chronology of Policy Flux and Legal Stagnation
The path to this current crisis began with a legislative push to curb federal spending and address the escalating student debt crisis. By restricting the availability of "easy" federal credit for graduate school, proponents argued that universities would be forced to lower tuition rates to remain competitive. However, the implementation of these rules triggered immediate backlash from the academic and health care sectors.
In the months leading up to the July 1 effective date, the Department of Education faced mounting pressure to clarify which programs qualified for the higher loan tiers. The uncertainty deepened when a coalition of nursing groups and professional health care associations filed a lawsuit, alleging that the arbitrary classification of programs threatened the pipeline of essential workers. In response, a federal judge issued an injunction suspending the implementation of the stricter rules until at least December.
This legal stay has created a "policy vacuum." Students applying for the 2027-28 academic year are currently operating in a landscape where the rules of the game could change mid-application. If the government prevails in court, students who enrolled under the assumption of higher borrowing capacity could find their funding sources drying up, forcing a sudden pivot to the private loan market.

The Financial Reality: Private Lenders and Risk Assessment
The potential shift toward private lending represents a significant departure from the stability of federal student aid. Private lenders operate under strict underwriting criteria that prioritize credit scores and projected income, often disregarding the social value of degrees in fields like occupational therapy, social work, or counseling.
Financial aid experts warn that this transition will disproportionately affect students from lower-income backgrounds. "We are seeing a trend where private lenders are becoming increasingly selective," noted Mark Kantrowitz, a noted expert in student financial aid. "They are targeting students in programs with historically high earning potential, like business or engineering, while leaving those in critical public service sectors—such as nursing and psychology—to face much higher barriers to entry."
The concern is not merely the availability of loans, but the predatory nature of the private market. Eileen Connor, director of the Project on Predatory Student Lending, highlights that private loans often lack the consumer protections built into the federal system. These include income-driven repayment plans, public service loan forgiveness, and, crucially, the ability to avoid mandatory arbitration clauses that limit a borrower’s legal recourse. In some instances, students with less-than-perfect credit profiles could face interest rates as high as 16 percent, a burden that could take decades to repay and effectively deter many from pursuing advanced degrees in essential fields.
Broader Economic Implications and Industry Responses
The ripple effects of this policy uncertainty extend far beyond individual classrooms. The nursing and health care sectors are already grappling with critical staffing shortages, particularly in rural and underserved areas. Kayce Cordray, a 44-year-old doctoral student in nursing at Oral Roberts University, suggests that the current instability serves as a deterrent for potential students. "If you don’t know what you are going to be allowed to borrow, are you really going to want to commit to a multi-year, expensive program?" she asked. For many in her position—often parents juggling work and family responsibilities—the risk is simply too high.
While some institutions are attempting to mitigate the damage, the response has been uneven. A select group of well-endowed universities has begun offering internal loan programs with lower interest rates to fill the gap left by federal limits. Others are publishing "preferred lender" lists to steer students toward more reputable financial institutions. However, these measures do not address the systemic issue of high tuition.
Opinions on the long-term impact of these limits remain divided. The American Enterprise Institute (AEI) has suggested that the policy will force a necessary market correction. According to AEI reports, if federal funds no longer cover the entirety of tuition at high-cost institutions, those schools will be pressured to reduce prices to prevent losing students to more affordable regional alternatives. Conversely, organizations like New America remain skeptical, arguing that there is little evidence that elite private universities will voluntarily lower tuition, regardless of federal lending caps.

The Human Cost: A Policy Vacuum
For students like Mitzie Westgate, the intellectual and social cost of this uncertainty is palpable. Westgate’s top choices include the Medical University of South Carolina, Quinnipiac University, and the University of New Hampshire. However, she has also had to consider Johnson & Wales University in her home state of Rhode Island, where she could live with her parents to minimize costs. While the latter is a sensible financial decision, it would mean graduating with a narrower network of professional contacts in her specific field of interest.
The situation is equally dire for those already in the workforce. Gracie Hayworth, who is pursuing an online master’s of public health, is now reconsidering her and her husband’s long-term academic plans. Because private loans often require repayment to begin while the student is still enrolled—unlike federal loans, which offer deferred payment—the financial math for many households no longer works. "We were sitting at the kitchen table deciding whether we can make this work," Hayworth explained. "If we have to manage loan payments while working toward a Ph.D., it creates an insurmountable barrier for many families."
Conclusion: The Need for Clarity
As the December deadline for the judicial ruling approaches, the higher education sector remains on edge. The National Association of Student Financial Aid Administrators has described the current climate as one of "whiplash," where financial aid directors are unable to provide definitive guidance to students and their families.
The core of the issue lies in the tension between fiscal responsibility and the accessibility of advanced professional training. Whether the current loan limits are upheld or overturned, the experience of the last year underscores a fundamental truth: the stability of the federal student aid system is a cornerstone of the American workforce pipeline. Until a final decision is reached, the next generation of therapists, nurses, and public health experts will continue to navigate their futures in the dark, forced to make life-altering decisions based on a policy environment that is as unpredictable as it is consequential. For now, the "playing it by ear" strategy remains the only option for those who refuse to let the current chaos dictate the ceiling of their professional potential.