On November 8, 2016, at 8:00 PM, Prime Minister Narendra Modi delivered a televised address that would irrevocably alter the landscape of the Indian economy. In a sudden, nationwide announcement, he declared that all 500- and 1,000-rupee banknotes—which collectively accounted for 86.9% of the total value of currency in circulation at the time—would cease to be legal tender at the stroke of midnight. The directive was framed as a "surgical strike" against the "black economy," a term used to describe the vast pool of unaccounted wealth circulating in India. The government’s stated objectives were ambitious: to flush out illicit cash, curb counterfeit currency, dismantle terrorist financing networks, and transition India toward a transparent, digital-first economic paradigm.
A Chronology of the Cash Crunch
The immediate aftermath of the announcement triggered a period of unprecedented national upheaval. As the government imposed strict limits on cash withdrawals, millions of citizens flooded into bank branches and ATMs across the country. The visual of long, snaking queues became a defining symbol of the period. For weeks, the supply of new 500- and 2,000-rupee notes failed to keep pace with the demand, leaving the population in a state of prolonged uncertainty.
The logistical failure was immediate. By mid-November 2016, reports emerged of rural populations—many of whom lacked traditional bank accounts—being effectively cut off from their own savings. Small-scale traders, farmers, and daily-wage laborers, who relied almost exclusively on cash for survival, found their operations paralyzed. By December 2016, the government had introduced a series of complex rules, including the exchange of old notes for new ones and the requirement to deposit the now-invalid currency into bank accounts, which led to intense scrutiny of household savings. The process concluded in late 2016, but the economic ripple effects continued well into 2017 and beyond.
The Economic Toll on the Informal Sector
The informal economy, which constitutes a significant portion of India’s GDP and employs the vast majority of its workforce, bore the brunt of the shock. According to various economic analysts, the liquidity crunch led to a temporary contraction in manufacturing and consumption. Businesses that operated on cash-on-delivery models or paid employees in physical currency struggled to meet their obligations.
Joe Athialy, executive director of the Center for Financial Accountability, emphasizes that the policy failed to account for the structural realities of the Indian market. "Demonetization was a policy implemented with a top-down assumption that failed to recognize how the poor interact with the economy," Athialy notes. "It was not merely a monetary adjustment; it was an event that disrupted the livelihoods of millions, many of whom never fully recovered from the loss of income during those months."
The tragedy of the situation was punctuated by reports of fatalities. Whether through stress-induced medical crises or the inability to pay for emergency healthcare due to the lack of liquid cash, the human cost of the transition became a point of significant political contention. Businessman Prakash Patra, reflecting on the period from Jaipur, recalls the desperation of the era: "I remember the domestic help’s father, who stood in line for days to exchange his life savings. He collapsed and died. It was a stark reminder that when policy ignores the ground reality of the vulnerable, the price is paid in human lives."
Evaluating the Stated Objectives: Where is the Black Money?
The government’s core promise was the eradication of "black money"—unaccounted wealth often stored in cash to evade taxes. However, the 2018 annual report from the Reserve Bank of India (RBI) delivered a sobering verdict. The central bank revealed that 99.3% of the demonetized notes had returned to the banking system. This statistic effectively dismantled the narrative that a significant portion of illicit cash would be permanently extinguished, as it implied that nearly all "black" money had been successfully laundered or deposited into bank accounts.
Economists have long argued that the government’s premise was fundamentally flawed. "The real black economy is not kept in mattresses as stacks of 500-rupee notes," explains former JNU professor Arun Kumar. "It is invested in real estate, gold, jewelry, and offshore tax havens. By focusing on cash, the government penalized the informal sector—the very people who rely on it—while leaving the real engines of illicit wealth largely untouched."
The Shift Toward Digital Payments
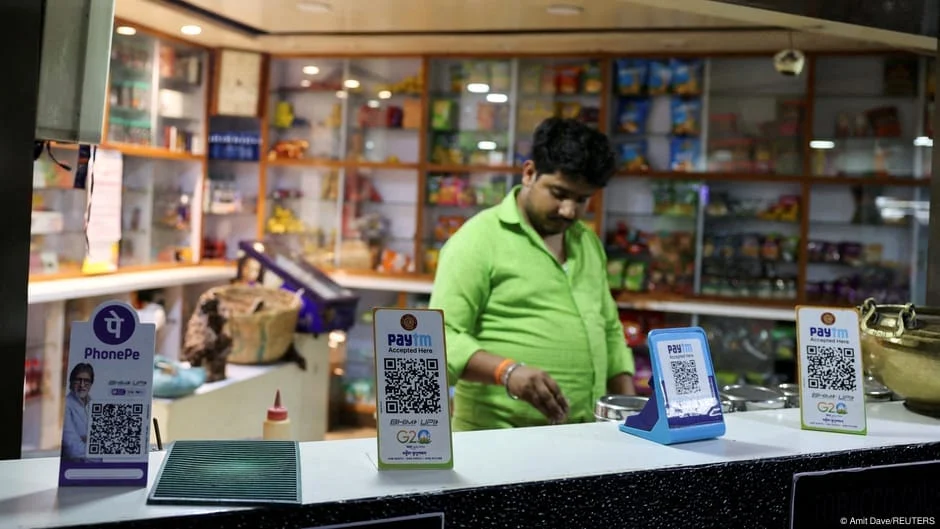
If the eradication of black money was the primary goal, the surge in digital transactions is often cited by the current administration as the most significant success of the policy. The Unified Payments Interface (UPI), which was in its infancy in 2016, has since transformed into a global benchmark for instant, peer-to-peer digital payments.
Data from the RBI for the 2025-26 fiscal year indicates that UPI processed a staggering 241.6 billion transactions, with a cumulative value of 314.2 trillion rupees. This shift has undeniably reduced the friction of retail transactions and integrated millions of Indians into the formal financial system. However, experts like Professor Lekha Chakraborty warn against a causal fallacy.
"Digital payments were already on an upward trajectory before November 2016," says Chakraborty. "The growth we see today is a result of improved internet penetration, lower data costs, and the natural evolution of the fintech ecosystem. While demonetization may have acted as a catalyst or a ‘nudge’ for some, attributing the entirety of the digital transformation to a single policy is not supported by long-term data trends."
The Persistence of Cash
Despite the meteoric rise of UPI, cash remains a dominant force in the Indian economy. Data from the RBI shows that the value of banknotes in circulation on October 23, 2026, reached 43.15 trillion rupees, significantly higher than the 17.97 trillion rupees in circulation just before the 2016 announcement. This growth in physical currency suggests that, despite the convenience of digital platforms, the demand for cash—driven by trust, anonymity, and the needs of the informal sector—remains as robust as ever.
The resilience of cash indicates that the "cashless" goal envisioned by policymakers has not materialized. Instead, India has developed a dual-currency system where digital payments and physical cash coexist, serving different segments of the population and different types of transactions.
Institutional Accountability and Long-Term Implications
A decade later, the question of institutional accountability remains unanswered. Critics point to the loss of autonomy within the Reserve Bank of India, noting that the decision-making process leading up to the announcement was shrouded in secrecy and lacked the traditional consultative rigor expected of a central bank.
The institutional cost, according to analysts, includes a temporary decline in public trust and the exhaustion of administrative resources that could have been directed toward more sustainable reforms. The lack of a formal, comprehensive inquiry into the consequences of the demonetization process continues to be a point of debate in policy circles.
Conclusion: A Legacy of Mixed Results
The legacy of the 2016 demonetization is multifaceted. On one hand, it spurred an infrastructure for digital finance that has placed India at the forefront of global payment technology. On the other hand, it stands as a case study in the perils of economic shock therapy. The intended goals—curbing corruption and eliminating black money—remain largely unfulfilled, while the unintended consequences—the disruption of livelihoods and the stress on the informal sector—left a lasting scar on the national memory.
As India continues to navigate its path toward becoming a global economic power, the lessons of 2016 serve as a reminder that structural changes to a complex, cash-dependent economy require more than just a sudden change in currency. They require sustained investment in institutional transparency, a deep understanding of the informal labor market, and a cautious approach to policies that fundamentally alter the everyday lives of the most vulnerable. While the debate over its necessity and execution continues, the facts remain clear: the move did not destroy the black economy, nor did it eliminate the reliance on cash. Instead, it accelerated a digital transition that was already inevitable, albeit at a cost that many argue was far too high.

