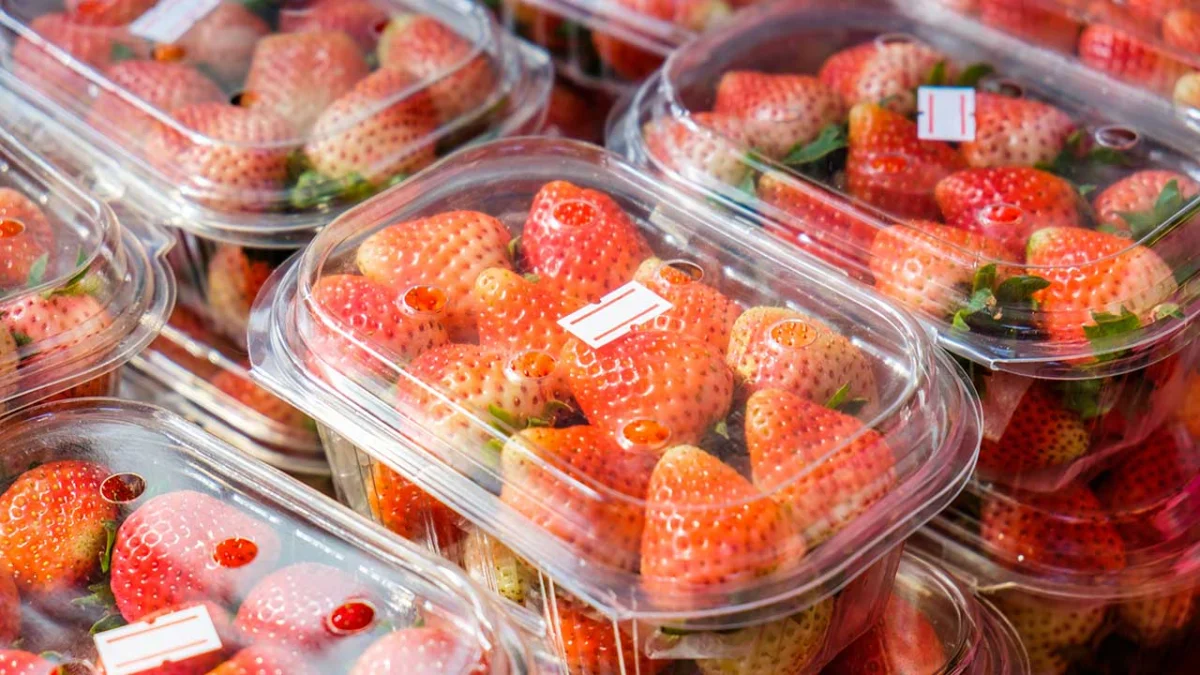
As consumers navigate grocery store aisles in the coming years, subtle but profound transformations will become increasingly visible. Fresh fruits, once encased exclusively in rigid plastic clamshells, will increasingly rest in ventilated cardboard packaging. Takeout salads will be served in durable fiber bowls, while microwaveable convenience meals transition away from traditional black plastic trays toward clear, easily sortable alternatives. These shifts are not merely passing corporate trends; they are the tangible outcomes of California Senate Bill 54 (SB 54), a landmark legislative act whose finalized regulatory framework took effect in May 2026.
While the statute was enacted within the Golden State, its implications extend far beyond the West Coast. Because major multinational manufacturers rarely maintain separate packaging lines exclusively for one jurisdiction, the legal mandates established in California are actively reshaping supply chains nationwide. The transition marks a pivotal turning point in how American commerce addresses single-use waste, introducing systemic accountability to an industry that has relied on lightweight, inexpensive polymers for decades.
The Scale of the Global Plastics Crisis
To fully grasp the mechanics and urgency of SB 54, it is necessary to examine the sheer volume of waste the legislation seeks to mitigate. For the better part of a century, synthetic plastics became the foundational material for global packaging due to their low cost, durability, and minimal weight. However, this explosive growth catalyzed an escalating environmental crisis.
According to historical data from the U.S. Environmental Protection Agency (EPA), plastic waste accounted for a negligible 0.4% of total municipal solid waste generated in the United States in 1960. By 2018, that figure had surged to 12.2%, reflecting an exponential rise in disposable goods. Packaging constitutes a substantial portion of this volume, as it is manufactured primarily for immediate disposal. Industry analyses indicate that approximately 36% of all newly produced plastic is dedicated to packaging applications, with a staggering 85% of that material ultimately terminating in municipal landfills.
In response to these compounding pressures, California lawmakers drafted SB 54, formally known as the Plastic Pollution Producer Responsibility Act. The legislation establishes two core mandates: a legally binding requirement to reduce single-use plastic packaging by 25% by 2032, and a mandate ensuring that all single-use packaging sold or distributed within the state is either genuinely recyclable or commercially compostable.
At the heart of SB 54 lies the economic framework of Extended Producer Responsibility (EPR). Historically, the financial burden of managing post-consumer waste fell squarely on local municipalities and taxpayers through public sanitation budgets. EPR shifts this fiscal responsibility directly onto the producers and brand owners who introduce the packaging into the marketplace. By internalizing the true cost of waste management, the law creates a powerful financial incentive for corporations to minimize material usage, redesign packaging for seamless recyclability, and eliminate problematic polymers altogether.
Legislative Timeline and Regulatory Milestones
The implementation of SB 54 follows a carefully structured, multiyear roadmap designed to give corporations adequate time to retool manufacturing facilities while holding them accountable to interim performance benchmarks.
The timeline officially commenced when finalized regulations took effect on May 1, 2026. By June 1 of that year, producers were required to formally register with the designated Producer Responsibility Organization (Circular Action Alliance), register independently with the state recycling agency CalRecycle, or apply for verified small-producer exemptions.
As the program matures, increasingly stringent requirements take effect:
- January 1, 2027: Full operational implementation begins. Covered single-use plastic packaging must be reduced by 10% relative to established 2023 baselines. Producers operating outside of an approved compliance plan are legally barred from selling covered materials in California, and initial mitigation fund payments commence. Consumers will likely observe thinner primary packaging and reduced secondary elements, such as promotional sleeves and oversized shipping boxes.
- January 1, 2028: The mandatory recycling rate threshold increases. At least 30% of covered single-use plastic packaging and food service ware must be physically recycled rather than simply classified as theoretically recyclable. This milestone accelerates the commercial adoption of materials easily identified by modern optical sorting infrastructure.
- January 1, 2030: The statutory recycling rate target rises to 40%, while the source reduction mandate escalates to 20%. During this phase, consumer-facing infrastructure such as refill stations, concentrated pods, and returnable container systems are expected to transition from pilot programs into mainstream retail offerings.
- January 1, 2032: The final statutory targets fully materialize. Producers must achieve a 25% source reduction, a 65% recycling and composting rate, and ensure that 100% of covered packaging meets strict recyclability or compostability standards. Regulators are granted the statutory authority to evaluate these outcomes and establish even more rigorous goals if necessary.
Immediate Material Phase-Downs and Redesigns
SB 54 exerts intense regulatory pressure on specific material categories that have historically complicated municipal sorting facilities and contributed disproportionately to environmental pollution.
Expanded Polystyrene (EPS), widely recognized by the brand name Styrofoam, faces severe restrictions. Commonly utilized in single-use coffee cups, takeout clamshells, and protective shipping blocks, EPS is composed primarily of trapped air, making long-distance transport economically inefficient. More critically, the material easily fragments into microscopic particles that contaminate clean recycling streams and devalue higher-quality materials. Public health research has further associated chronic exposure to styrene—a foundational chemical in polystyrene production—with elevated risks of leukemia, lymphoma, and other serious medical conditions. In alignment with these concerns, California prohibited the sale and distribution of EPS food service ware following the industry’s failure to meet interim recycling benchmarks.
Black and dark-colored plastic packaging, frequently utilized for prepared meal trays and sushi containers, presents an operational challenge for recycling facilities. Modern material recovery facilities (MRFs) rely heavily on near-infrared (NIR) optical sorters to rapidly identify and segregate different polymer types. However, the carbon black pigments traditionally used to color these trays absorb near-infrared light rather than reflecting it, rendering the items invisible to automated sorting equipment. Consequently, these packages bypass automated recovery lines and are diverted to landfills. Under SB 54, manufacturers are rapidly pivoting toward clear or light-colored polyethylene terephthalate (PET), aluminum, and molded fiber alternatives that optical sorters can efficiently process.
Polyvinyl chloride (PVC), frequently found in clear clamshell containers for berries, bakery goods, and protective retail blister packs, is another primary target. PVC functions as an aggressive contaminant within the standard PET recycling stream; even microscopic traces of vinyl can compromise an entire industrial bale of PET, rendering it unsalvageable. Furthermore, plasticizers utilized to increase the flexibility of PVC often contain phthalates, chemicals associated with endocrine disruption and chronic metabolic conditions. Regulatory pressures are driving brands toward recycled PET (rPET) and unbleached paperboard alternatives.
Finally, oxo-degradable plastics—conventional petroleum-based polymers infused with chemical additives designed to accelerate fragmentation when exposed to heat and ultraviolet light—face strict scrutiny. Rather than truly biodegrading into organic compounds, these materials break down into persistent microplastics that infiltrate agricultural soils and aquatic ecosystems. SB 54’s rigorous anti-greenwashing provisions effectively restrict the marketing of such materials unless they can prove complete biological assimilation under certified scientific standards.
Industry Pushback and Legal Challenges
Despite the structured timeline and widespread environmental backing, the implementation of SB 54 has not proceeded without friction. Environmental advocacy organizations, including Oceana, the Natural Resources Defense Council (NRDC), and the Californians Against Waste Foundation, filed a formal lawsuit in the San Francisco Superior Court challenging aspects of the finalized regulations.
The plaintiffs argue that the regulatory text adopted by state agencies contains broad exemptions for major categories of plastic packaging, permits producers to claim indefinite compliance extensions, and fails to adequately restrict advanced chemical recycling technologies that environmental groups contend run counter to the foundational goals of source reduction. These legal proceedings underscore the intense economic and political stakes involved, as corporate stakeholders balance compliance costs against potential liabilities.
Broader Economic Implications and National Precedent
The ripple effects of California’s legislation are fundamentally altering commercial strategies across the United States. Because California represents the nation’s largest consumer market, maintaining separate packaging inventories tailored exclusively to state boundaries is economically impractical for major manufacturing conglomerates. Consequently, companies are adopting a "highest common denominator" approach, redesigning their packaging suites to meet California’s stringent criteria for nationwide distribution.
This dynamic is accelerating a broader movement toward regional and federal policy harmonization. Several states have enacted or proposed parallel Extended Producer Responsibility frameworks for packaging. Oregon’s Recycling Modernization Act enforces similar producer-funded modernization of municipal recovery systems. States including Colorado, Maine, and Vermont have implemented analogous EPR statutes, while legislative bodies in states like New York continue to advance similar frameworks.
In the absence of a unified federal EPR statute, this state-level legislative activity is rapidly establishing a de facto national standard. For multinational brands, navigating this evolving regulatory landscape requires unprecedented investments in sustainable packaging engineering, supply chain transparency, and lifecycle analysis.
The Consumer Role in a Circular Economy
While the statutory weight of SB 54 falls primarily on manufacturers and commercial distributors, the legislation ultimately relies on active consumer participation to achieve its long-term objectives. Shoppers navigating retail environments are encouraged to look for verified third-party certifications rather than relying on ambiguous marketing terminology.
Labels such as the Biodegradable Products Institute (BPI) certification provide verified assurance that a product will safely break down in commercial composting facilities, while standardized recycling labels offer explicit instructions regarding municipal disposal pathways. As corporate compliance efforts expand through 2032, informed consumer purchasing decisions will continue to reinforce market shifts toward true circularity, transforming public infrastructure and reducing the environmental footprint of modern commerce.

